Solar panels can turn an unused warehouse roof into a productive business asset. Yet the purchase price is only part of the decision. Businesses may receive solar tax credits because governments want to encourage cleaner electricity, private investment, and lower emissions. A credit can reduce taxes owed, improving a project’s financial return. It is not a cash discount at checkout. The benefit usually depends on eligible equipment, installation dates, ownership structure, and documented costs. Rules also change, and local programs may sit beside national incentives.
So, How do solar tax credits work for businesses? In general, a qualifying company calculates an approved credit and applies it against its tax liability. Some businesses may use depreciation alongside the credit, subject to applicable rules. A partnership, corporation, nonprofit, or tax-exempt entity may face different pathways. Transfer, direct-pay, and financing options can also affect the outcome. The practical details matter. Invoices, commissioning records, interconnection evidence, and tax forms may support a claim. Missing paperwork can weaken an otherwise sound project.
The strongest analysis compares the credit with installation costs, energy savings, maintenance, financing, and possible recapture risks. A rooftop system producing power at noon may not match a factory’s evening demand. Battery storage can change that calculation, but it adds cost and technical questions. No incentive should be treated as guaranteed profit. Eligibility may depend on changing legislation and official guidance. This article explains the main business reasons for these credits, their effect on project economics, and the assumptions requiring careful review. A qualified tax professional should verify the final position before filing.
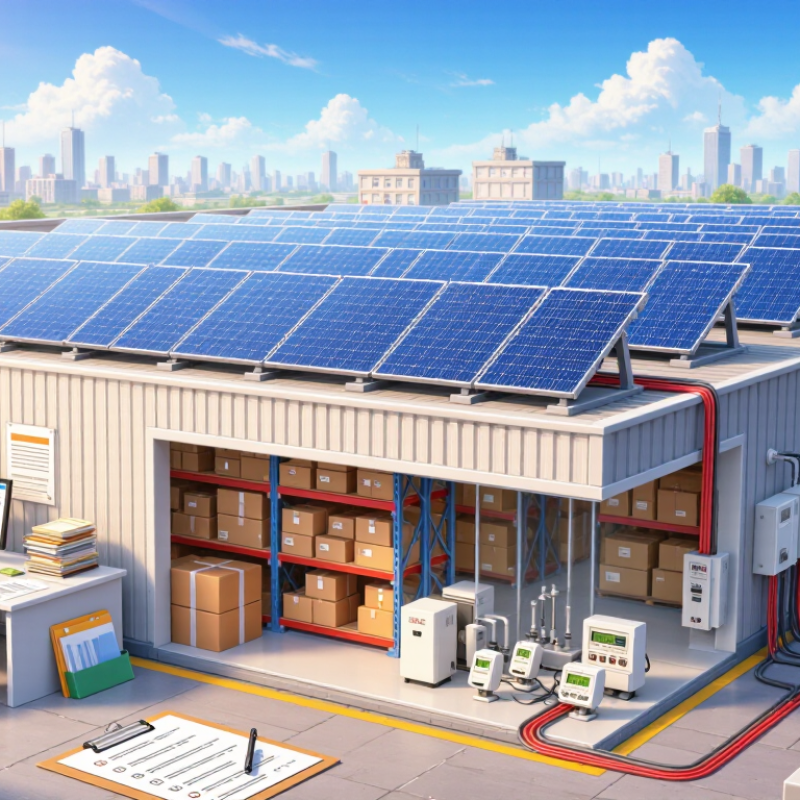
Solar tax credits are financial incentives that reduce a business’s tax bill after installing an eligible solar energy system. Unlike a deduction, which lowers taxable income, a credit directly reduces taxes owed. Rules differ by country, state, and project structure, so eligibility must be checked carefully.
A business may use a credit to make solar equipment more affordable. Imagine a warehouse adding rooftop panels, inverters, wiring, and monitoring equipment. The finance team records installation costs, confirms the system’s operating date, and keeps contracts, invoices, permits, and inspection documents. These records help support the claim during tax preparation. Some programs also offer extra incentives for storage, local labor, or projects in specific communities.
The benefit is not only immediate savings. Solar can reduce monthly electricity expenses and make energy costs easier to forecast. However, a tax credit may not cover every project cost, and a company with little tax liability might not use the full amount immediately. Financing can add interest, fees, and timing issues. Rules may also change before construction ends. The process is rarely perfect. A carefully designed project can still face delays, missing paperwork, or unexpected grid-connection charges. Businesses should ask a qualified tax professional and an energy adviser to review eligibility, tax capacity, construction timing, and documentation before relying on projected savings.
| Tax Credit or Benefit | How It Works | Typical Business Value | Main Eligibility Conditions | Why Businesses Use It |
|---|---|---|---|---|
| Investment Tax Credit (ITC) | A percentage of eligible solar project costs is claimed as a federal income tax credit. | The base credit is generally 30% for qualifying projects that meet applicable prevailing-wage and apprenticeship requirements. | The project must qualify under federal energy-credit rules, and construction and placed-in-service dates must satisfy the applicable law. | It can substantially reduce the upfront after-tax cost of purchasing and installing a solar energy system. |
| Domestic Content Bonus | An additional credit percentage may be available when required portions of the project’s steel, iron, and manufactured components meet domestic-content standards. | Generally an additional 10 percentage points when all applicable requirements are satisfied. | The project must satisfy detailed statutory domestic-content thresholds and documentation requirements. | It can increase the total credit while encouraging the use of qualifying domestic materials and components. |
| Energy Community Bonus | A qualifying project located in an energy community may receive an additional percentage-point increase to the ITC. | Generally an additional 10 percentage points, subject to location and project requirements. | The site must meet the applicable definition of an energy community, which may involve fossil-fuel employment, tax-base, or brownfield criteria. | Businesses may receive a larger credit while investing in areas affected by changes in energy production or employment. |
| Low-Income Communities Bonus | Certain solar and other clean-energy projects may receive an allocation-based bonus credit for serving eligible low-income communities or housing developments. | The bonus is generally 10 or 20 percentage points, depending on the qualifying category and approved allocation. | Projects generally require an allocation under the applicable federal program and must satisfy additional eligibility rules. | The incentive can improve project economics while expanding access to solar benefits in underserved communities. |
| Production Tax Credit (PTC) | A credit is earned according to the amount of qualified electricity produced and sold or used during the credit period. | For qualifying projects meeting labor requirements, the inflation-adjusted full-rate credit is approximately 2.75 cents per kilowatt-hour for electricity produced in 2024; rates are adjusted under federal rules. | The facility must meet applicable technology, construction, labor, and electricity-production requirements. | It may be more valuable than the ITC for projects with strong, predictable electricity production over time. |
| Choice Between ITC and PTC | For a qualifying facility, the business generally evaluates whether a cost-based ITC or production-based PTC provides the greater financial benefit. | The result depends on project cost, expected output, useful life, electricity prices, and tax position. | The same project generally cannot claim both credits for the same qualifying investment. | The choice allows businesses to align the incentive with their project design and expected operating performance. |
| Direct Pay | Certain eligible tax-exempt and governmental entities may receive a cash payment instead of using the credit to reduce federal income tax. | The payment can generally equal the value of an otherwise allowable credit when all requirements are met. | Eligibility is limited to specified entities and requires registration, pre-filing procedures, and timely tax filings. | It makes federal clean-energy incentives accessible to organizations that do not normally pay federal income tax. |
| Transferability | Eligible taxpayers may transfer certain federal clean-energy tax credits to an unrelated buyer for cash, subject to statutory requirements. | The project owner can convert an otherwise unused tax credit into project funding, with pricing negotiated between the parties. | The parties must meet federal registration, documentation, payment, and reporting requirements. | It can improve liquidity and reduce reliance on traditional tax-equity financing. |
| Accelerated Depreciation | Eligible solar property may qualify for accelerated tax depreciation under applicable federal depreciation rules, separate from the tax credit. | The benefit is based on the business’s tax rate, depreciable basis, and the depreciation schedule allowed for the property. | The business generally must own the property and place it in service for use in a trade or business, subject to tax rules. | It can create additional tax deductions and improve the project’s overall after-tax return. |
Note: Credit rates, labor requirements, bonus-credit rules, construction deadlines, and eligibility conditions depend on federal law and official guidance in effect when a project is developed and placed in service. Businesses should confirm the applicable rules with a qualified tax adviser.
It directly reduces a business’s taxes after installing an eligible solar energy system. A deduction works differently. A credit lowers the tax bill itself.
A qualified project may receive a 30% federal credit through 2032, subject to current rules. For a $1 million system, the potential tax value could reach $300,000. That figure is not guaranteed.
Records may include panels, inverters, wiring, monitoring equipment, permits, and installation invoices. Keep contracts and inspection documents together. Missing paperwork can weaken a valid claim.
Not always. A company with limited tax liability may not use the entire credit at once. Transfer or carryforward options may help, depending on current rules.
Large eligible projects may need to pay required local wage rates. Qualified apprentices and documented labor hours may also be required. Meeting these rules can protect the full credit value.
Keep payroll records, time sheets, wage determinations, apprentice ratios, and correction payments. Check subcontractor records too. Small gaps can become expensive.
Lower taxes can reduce project costs and improve cash flow. Solar may also lower monthly electricity expenses. Financing can still add interest, fees, and timing pressure.
Review construction dates, tax capacity, labor compliance, equipment costs, maintenance, and grid-connection charges. Rules may change before construction ends. The model may be wrong.
A qualified tax professional and energy adviser should check eligibility, timing, and documentation. A labor specialist may review wage records. Outside review is not wasted effort.
Businesses use solar tax credits to reduce the upfront and long-term cost of installing commercial solar systems. How do solar tax credits work for businesses? The federal Investment Tax Credit can cover 30% of eligible project costs through 2032, allowing companies to subtract a significant portion of their solar investment from federal tax liability. This benefit can improve project cash flow, shorten payback periods, and make clean energy upgrades more financially attractive.
Solar projects may also qualify for accelerated depreciation under the Modified Accelerated Cost Recovery System, enabling businesses to deduct equipment costs over a shortened schedule and gain additional tax benefits. For larger installations, meeting prevailing-wage and apprenticeship requirements is important because these standards help preserve the full credit value. Strong solar growth in 2024 further demonstrates how tax incentives are encouraging businesses to invest, lower operating expenses, manage energy risks, and support long-term sustainability goals.
 RayBoost Solar